
TL;DR
Codex can validate a saved strategy, create an inactive draft and run a historical comparison through NexusTrade. The five dividend grower simulation returned 44.80% versus SPY's 33.99% from January 2025 through October 7, 2026, but 340.90% versus 419.23% from January 2014. Candidate transactions cost 0.1%; the displayed SPY benchmark pays no candidate commissions. After an interruption, continue the accepted test rather than submit another.
Explore the completed 2025 through 2026 test
Portfolio value (USD)
- Five dividend growers 2026-10-07
- $14,479.88
- SPY buy and hold 2026-10-07
- $13,399.03
Five dividend growers: 22.41% largest decline in plotted observations. 2025-02-13 ($10,415.39) to 2025-04-08 ($8,081.82).
- Strategy return
- 44.80%
- SPY return
- 33.99%
- Maximum drawdown
- 24.33%
- Strategy fees
- $24.15
Recorded historical simulation: Jan 02, 2025 to Oct 07, 2026. Initial capital was $10,000.
Recorded in NexusTrade on October 8, 2026. Strategy assumptions: fractional shares, reinvested dividends and a 0.1% stock transaction fee. The stored SPY benchmark pays no candidate commissions.
Connect Codex in this workspace
codex mcp add nexustrade --url https://nexustrade.io/api/mcp
codex mcp login nexustrade
Scroll horizontally to read the full command, or copy it.
Inspect the request
Run these commands in the project folder where you will use Codex. Complete NexusTrade OAuth, start Codex and use /mcp to inspect the connection.
Try this example in Codex
Inspect the request
Connect Codex, then copy the request below. Review the returned result before continuing.
The rules behind this result
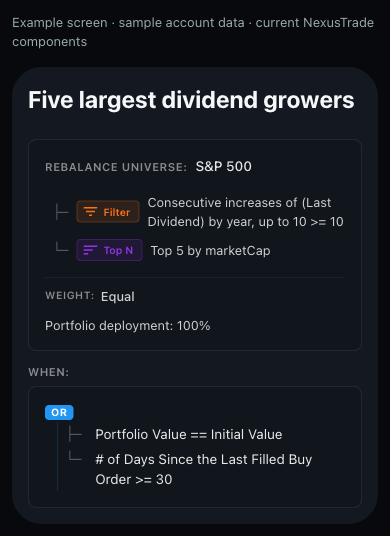
- Allocation trigger
- Review allocations when portfolio value equals its initial value OR at least 30 days have passed since a filled buy. This is not an exact monthly schedule.
- Equal weights
- Each selected company has the same weight: five qualifying companies would target 20% each before execution effects.
- Execution assumptions
- Fractional shares and reinvested dividends; the original stock fee was 0.1% per transaction.
From the S&P 500 universe, keep companies meeting the ten-year annual dividend-increase filter, select the five largest by market value and weight them equally. The target is 100% invested.
Create and read back the exact strategy
Use the reviewed configuration at https://nexustrade-prod.nyc3.cdn.digitaloceanspaces.com/Explore/Data/existing-dividend-five-configuration-20261010-2468740bdaf783a8.json. Ask your client to pass that complete object to build_portfolio, inspect valid and issues, then show the canonical portfolio. After reviewing it, save the same JSON with create_portfolio and read the returned chat draft with get_portfolio. Keep the draft ID in your experiment record.
Check the SP500 universe, dividend filter, market-cap ranking, five selected names, equal weights, full deployment, 30-day trigger, fractional shares and reinvestment against the reviewed configuration. Keep the new draft undeployed while testing.
Reproduce the five-dividend-growers experiment in Codex. Read the exact configuration at https://nexustrade-prod.nyc3.cdn.digitaloceanspaces.com/Explore/Data/existing-dividend-five-configuration-20261010-2468740bdaf783a8.json. Pass the complete configuration to build_portfolio. Show valid, issues and canonical rules. Preserve the universe, filter, ranking, weighting, rebalance trigger, fractional shares and dividend policy. After I approve the rules, save the same JSON with create_portfolio, then read the returned portfolio_id with get_portfolio. Record that chat draft ID. Stop before backtesting or deployment.Submit the matching historical test
Continue only when the connected client has the required authoring and backtest tools. Review the dates, capital, fee and dividend assumptions, and research-token cost before approving one test.
Replace the placeholder with the returned chat draft ID. Review these inputs, then approve one backtest_portfolio call. They match the displayed 2025 run. Save the accepted backtest ID before leaving the conversation.
generate_events is false for the curve comparison. Enable it when you want to inspect individual signals and orders; detailed event capture uses more credits. Keep all other settings fixed when making that inspection run.
Show the table · 7 rows, 2 columns
| Input | Explicit choice |
|---|---|
| portfolio_id | Exact returned chat draft ID |
| start_date / end_date | 2025-01-02 / 2026-10-07 |
| interval | Day |
| initial_value | 10000 |
| baseline_symbol | SPY |
| fee_config / dividend_policy | Stock: 0.1 percent; reinvest |
| generate_events | false for the curve; true for detailed signal and order inspection |
No matching rows. Clear the filter to see all records.
{
  "portfolio_id": "REPLACE_WITH_RETURNED_CHAT_ID",
  "start_date": "2025-01-02",
  "end_date": "2026-10-07",
  "interval": "Day",
  "initial_value": 10000,
  "baseline_symbol": "SPY",
  "generate_events": false,
  "dividend_policy": "reinvest",
  "fee_config": {
    "Stock": {
      "amount": 0.1,
      "type": "percent"
    }
  }
}
Tool reference
Validate a new candidate
NexusTrade toolbuild_portfolio
ReviewCanonical configuration and component issues; nothing is saved
Save the validated draft
NexusTrade toolcreate_portfolio
ReviewUse the reviewed configuration and retain the returned chat portfolio ID
Read the saved book
NexusTrade toolget_portfolio
ReviewExact strategies, action sizing, and portfolio identity
Submit the historical test
NexusTrade toolbacktest_portfolio
ReviewExplicit dates, interval, capital and benchmark
Poll the same operation
NexusTrade toolquery_backtest_status
ReviewTerminal state and warnings; do not resubmit while running
Inspect the curve
NexusTrade toolquery_backtest_history
ReviewHistorical values for the returned backtest_id
Compare candidates
NexusTrade toolcompare_backtests
ReviewIdentical period and assumptions, with activity and risk
Inspect the tool operations for this experiment
Scroll sideways to compare all columns. Select a heading to sort.
| Validate a new candidate | build_portfolio | Canonical configuration and component issues; nothing is saved |
| Save the validated draft | create_portfolio | Use the reviewed configuration and retain the returned chat portfolio ID |
| Read the saved book | get_portfolio | Exact strategies, action sizing, and portfolio identity |
| Submit the historical test | backtest_portfolio | Explicit dates, interval, capital and benchmark |
| Poll the same operation | query_backtest_status | Terminal state and warnings; do not resubmit while running |
| Inspect the curve | query_backtest_history | Historical values for the returned backtest_id |
| Compare candidates | compare_backtests | Identical period and assumptions, with activity and risk |
No matching rows. Clear the filter to see all records.
Inspect the discovered inputs before submitting a call. For a new candidate, validate and save it first; for a saved candidate, start with get_portfolio. Record the portfolio and backtest identifiers returned by the account tools.
Inspect the completed curve and explain a rebalance
Poll query_backtest_status with the accepted backtest_id. PENDING or RUNNING means continue with that same ID. Resolve a reported ERROR before changing the experiment. Once complete, read query_backtest_history and follow pagination for the full period. Save the completed statistics and history with the rules and inputs.
Compare value with comparisonValue, then follow cash and positionValue around a rebalance or drawdown. With detailed events enabled, ask the client to read query_backtest_events and explain which condition fired, which stocks qualified, how weights changed and which orders filled. Keep the explanation tied to returned records.
Detailed signal traces
The original example used generate_events:false. A new generate_events:true test costs 5× research tokens; review that request before submitting it and read query_backtest_events while its three-day traces are retained.
Use the accepted backtest_id to poll query_backtest_status until complete. Then read query_backtest_history with that same ID, page 1 and page_size 500; follow all pages. Show the strategy and SPY curves, return, maximum drawdown and fees for 2025-01-02 through 2026-10-07. Explain one rebalance or drawdown using cash, holdings and recorded order events when available. Preserve the returned IDs and source fields in the experiment record. Keep polling the existing test rather than submitting another.Compare the other recorded periods
Show the table · 3 rows, 6 columns
Scroll sideways to compare all columns. Select a heading to sort.
| 2025-01-02 | 44.80% | 33.99% | 24.33% | 49 | $24.15 |
| 2022-01-03 | 134.94% | 73.13% | 24.16% | 153 | $103.47 |
| 2014-01-02 | 340.90% | 419.23% | 24.16% | 422 | $331.98 |
No matching rows. Clear the filter to see all records.
The same rules also have completed runs starting in 2022 and 2014. Compare the full period table before selecting a variant; the long 2014 run returned less than SPY.
Inspect the longer recorded period
Portfolio value (USD)
- Five dividend growers 2026-10-07
- $44,089.69
- SPY buy and hold 2026-10-07
- $51,922.83
Five dividend growers: 22.80% largest decline in plotted observations. 2014-11-21 ($10,674.15) to 2015-08-25 ($8,240.24).
Inspect the 2014 through 2026 curve
- Strategy return
- 340.90%
- SPY return
- 419.23%
- Maximum drawdown
- 24.16%
- Strategy fees
- $331.98
Recorded historical simulation: Jan 02, 2014 to Oct 07, 2026. Initial capital was $10,000.
These examined periods are development evidence. Historical S&P 500 membership at each date is not established by this receipt; the 2014 run is a retrospective simulation rather than proof of an investable selection.
Connect Codex in the workspace you will use
Connect Codex in the workspace you will use
In the desktop app, open Settings, MCP servers and Add server. Name it nexustrade, choose Streamable HTTP and paste the endpoint below. Save, select Restart, then Authenticate and complete NexusTrade sign-in. In the composer, /mcp shows connected servers.
For CLI use, run the commands below in your research workspace, finish browser OAuth, then start codex. Desktop and CLI configuration is local; verify tools in the task where you will run the workflow.
codex mcp add nexustrade --url https://nexustrade.io/api/mcp
codex mcp login nexustrade
codex mcp list
Confirm access with an owned-resource read
Confirm access with an owned-resource read
Ask the client to discover tools and call fetch_portfolios, then pass one returned portfolioId as portfolio_id to get_portfolio. Inspect portfolioId, type, name, isActive and strategies; compare them with the same saved book in NexusTrade. Do not copy IDs from a demonstration. An empty list can be valid for a new account.
A tool-not-found error means revisit discovery. An authorization error means check the selected NexusTrade environment/account and OAuth connection. Do not ask the model to invent a replacement identifier.
Use only NexusTrade read tools. Call fetch_portfolios, then pass one returned portfolioId as the portfolio_id input to get_portfolio. Show portfolioId, type, name, isActive and complete strategies. Do not create, edit, backtest, deploy or place orders.Create one variant, then test unseen dates
Save a separate variant that changes only SelectTop.limit from five to ten. Keep the universe, dividend filter, weights, capital, fees, interval and development dates fixed. Record both configurations and their completed backtest IDs before comparing return, drawdown, holdings and turnover.
After choosing a candidate, freeze its configuration and decision criteria. The three displayed historical periods have already been inspected. Select another chronological period you have not used in the example, corpus search or variant selection, then evaluate the frozen candidate once. Keep further revisions in a new research cycle. An optional final lockbox follows the same rule.
Reconnect Codex and continue the recorded test
Reconnect Codex and continue the recorded test
If the server is missing, inspect the selected local MCP configuration. If it requires OAuth, use Authenticate in the app or codex mcp login nexustrade in the CLI. After updating the desktop entry select Restart, then check /mcp. Reopen the saved artifact before continuing a new Codex task; a fresh conversation does not establish which operation was accepted.
For a disconnected session, reopen the saved backtest ID and query its status. If an accepted ID is missing, inspect the previous response before another submission; arbitrary new requests are not idempotent retries.
Keep the recorded experiment
Save the exact configuration, draft ID, accepted backtest ID, inputs and completed result together. Reopen that record after a connection interruption and continue polling the accepted run. Before paper trading, review a separate paper draft and observe its actual deployed history.
Exact strategy configuration
Inspect the complete strategy JSON
{
  "initialValue": 10000,
  "supportsFractionalShares": true,
  "dividendPolicy": "reinvest",
  "strategies": [
    {
      "active": true,
      "condition": {
        "lhs": null,
        "rhs": null,
        "comparison": null,
        "type": "Or",
        "conditions": [
          {
            "lhs": {
              "compound": false,
              "targetAssets": [],
              "type": "PortfolioValue"
            },
            "rhs": {
              "compound": false,
              "targetAssets": [],
              "type": "InitialValue"
            },
            "comparison": "equal",
            "type": "Base"
          },
          {
            "lhs": {
              "compound": false,
              "targetAssets": [],
              "side": "Buy",
              "type": "DaysSinceOrder",
              "orderStatus": "Filled"
            },
            "rhs": {
              "compound": false,
              "targetAssets": [],
              "value": 30,
              "type": "Value"
            },
            "comparison": "greaterThanOrEqual",
            "type": "Base"
          }
        ]
      },
      "action": {
        "type": "DynamicRebalance",
        "universe": {
          "source": "SP500"
        },
        "pipeline": [
          {
            "type": "Filter",
            "condition": {
              "lhs": {
                "compound": true,
                "targetAssets": [],
                "type": "ConsecutiveIncrease",
                "maxLength": 1,
                "period": "Year",
                "lookback": 10,
                "indicators": [
                  {
                    "compound": false,
                    "targetAsset": {
                      "type": "",
                      "symbol": ""
                    },
                    "targetAssets": [],
                    "type": "LastDividend"
                  }
                ]
              },
              "rhs": {
                "compound": false,
                "targetAssets": [],
                "value": 10,
                "type": "Value"
              },
              "comparison": "greaterThanOrEqual",
              "type": "Base"
            }
          },
          {
            "type": "SelectTop",
            "metric": {
              "compound": false,
              "targetAsset": {
                "type": "",
                "symbol": ""
              },
              "targetAssets": [],
              "type": "Fundamental",
              "metric": "marketCap"
            },
            "limit": 5,
            "direction": "Highest"
          }
        ],
        "weightIndicator": {
          "compound": false,
          "targetAssets": [],
          "value": 1,
          "type": "Value"
        },
        "deploymentPercent": {
          "compound": false,
          "targetAssets": [],
          "value": 100,
          "type": "Value"
        }
      },
      "orderExecution": {
        "type": "Market"
      },
      "automaticOrderApproval": false
    }
  ],
  "name": "Five largest dividend growers",
  "cash": 10000,
  "buyingPower": 10000,
  "supportsCrypto": false,
  "alertsEnabled": false
}
Chart range diagnostics
Inspect plotted ranges and their baseline
Five dividend growers plotted range
-18.18% to 48.99% from its first stored close.
SPY buy and hold plotted range
-15.08% to 35.08% from its first stored close.
Five dividend growers plotted range
-16.96% to 351.51% from its first stored close.
SPY buy and hold plotted range
-4.78% to 422.24% from its first stored close.
Continue after a Codex connection or test interruption
NexusTrade or a tool is missing
Use /mcp in the active task. Authenticate in the app or run codex mcp login nexustrade in the CLI. Restart the desktop server entry after editing it. Confirm build_portfolio, create_portfolio, backtest_portfolio, query_backtest_status and query_backtest_history are available before starting this workflow.
An ID is rejected
Use the portfolio_id or backtest_id returned to your own connected account. A demonstration ID or redacted receipt is not an identifier for your new test.
The test is PENDING or RUNNING
Poll query_backtest_status with the same accepted backtest_id. Continue the accepted operation after reconnecting rather than submitting another test.
The test reports ERROR
Retain the returned error and exact request. Resolve that cause before changing the experiment or approving another submission.
History or detailed events are unavailable
Backtest history is retained for 30 days. Detailed events require generate_events:true and are retained for three days. Save the completed result when it returns; enabling events costs 5× research tokens.
No comments yet.