TL;DR
The five-window NVDA/NVD sweep joined to a 14.13% historical return versus the matched NVDA price path's 49.20%, with smaller daily-point drawdown, 10.53% versus 21.25%. Each test restarted at $10,000, so the chain is not a continuous account. Earlier prices selected among 36 settings per window, including a negative validation winner. A first-window detailed replay differed by 0.1582 percentage points without explanation; these inspected dates remain retrospective evidence.
Watch the rules change before each later test
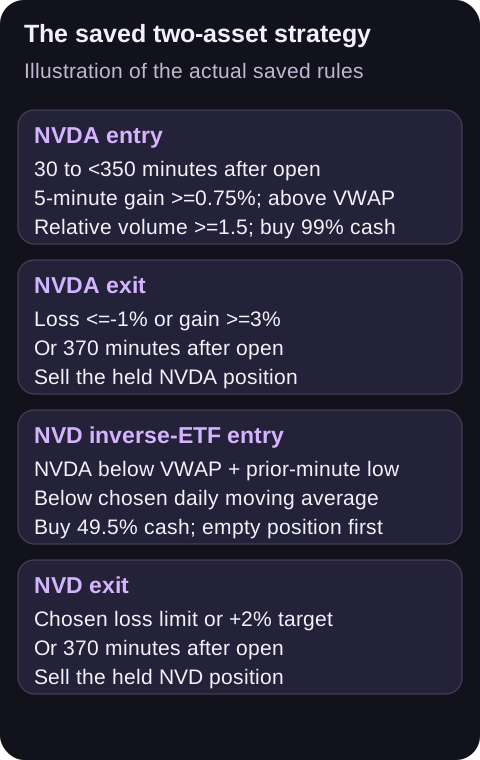
Start with the actual buy and sell rules
The strategy buys NVDA after a short price rise above VWAP, the average price weighted by trading volume. It can instead buy NVD, an inverse ETF designed to move opposite NVDA, when NVDA falls below its trend filters. Both entries require no NVDA or NVD position. Each side has a loss limit, profit target and late-session exit. The sweep changes only three settings on the NVD side; it does not search for a new strategy from scratch.
- Starting capital per test
- $10,000
- Costs
- 0.05% of each stock order's value
- Evaluation
- Minute; fractional shares; cash dividends
The saved strategy has four rules: an entry and exit for each asset. The exact configuration also retains session filters, cooldowns and holiday exclusions.
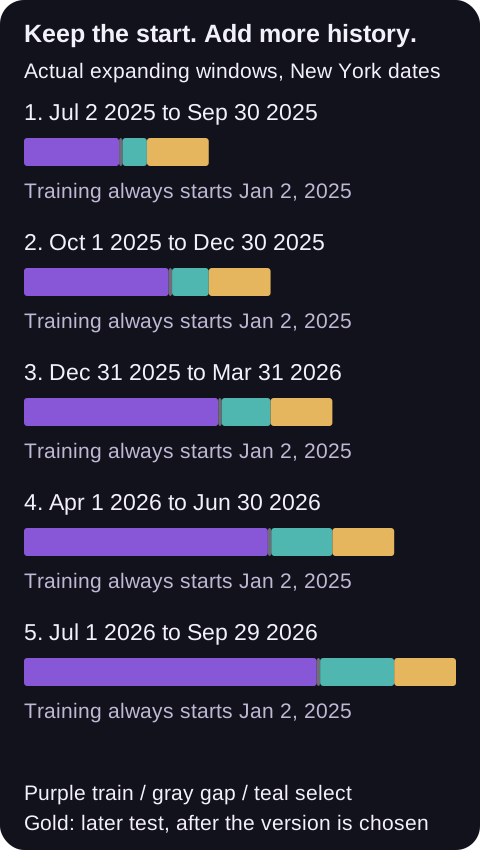
Add history, then test the next window
Purple builds candidates. Teal chooses among them after a five-day gap. Gold tests the selected version on later prices. Every purple bar starts on January 2, 2025, so these are expanding windows. A rolling plan would move the training start forward; that was not the plan run here. Read each displayed window label as Later test; it does not describe the full training-to-test bar.
All five later tests follow their own training and validation periods. No later result is used to choose that window’s version.
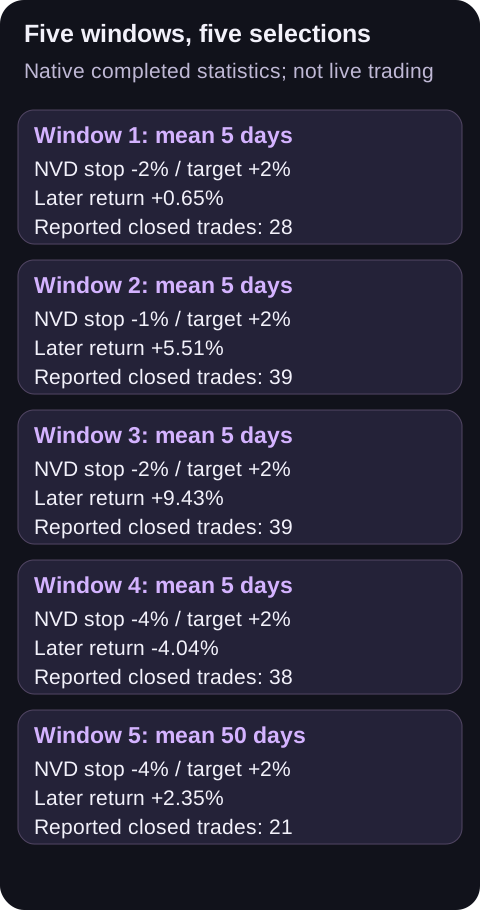
Read what each window selected
The selector chose the highest validation percent return, with no activity constraints. It picked a 5-day mean four times, then 50 days. Stops changed too. Window 5’s selected validation return was -1.11%: being the best available candidate did not mean its validation return was positive.
- Search per window
- 4 means × 3 stops × 3 targets = 36 combinations
- Completed study
- 185/185 units; COMPLETE
The five selected configurations differ in mean length or stop. The later returns belong to those exact versions, not one rule set reused throughout.
- Five tests, joined percentage changes 2026-09-29, 20:00:00 EDT
- 11,412.66
- NVDA holding price path 2026-09-29, 20:00:00 EDT
- 14,920.48
Compare the outcome with simply holding NVDA
Across the five tests, the joined return was 14.13%, versus 49.20% for the matched NVDA price path. The strategy lost less from its recorded peaks, but earned less overall. Each test starts with $10,000. This chart joins their percentage changes; it is not one account trading continuously.
- Strategy: largest drop at daily points
- 10.53%
- NVDA: largest drop at daily points
- 21.25%
The longer result did not beat holding NVDA on return. A smaller drop from recorded peaks answers a different question.
Open the complete experiment in Aurora
Open the filled-in request, review the exact settings, then send it to Aurora. It asks for a plan and cost review before any paid launch. Repeating these published dates reproduces historical research. For your own new check, choose dates excluded from every earlier rule change and search.
Inspect your saved research in OptimizationAurora receives the complete four-rule seed and three exact sweep selectors in your editable composer. Opening the request does not send it, start research or activate trading.
Walk-forward optimization chooses a version using earlier prices, then tests that frozen version on the next dates. This completed NVDA/NVD example searched 36 settings in each of five windows. The last window selected a 50-day moving average after four selections of 5 days.
Inspect the complete rules, costs and each measured period
Show the table · 5 rows, 6 columns
Scroll sideways to compare all columns. Select a heading to sort.
| 1 | 11.23% | 1.20% | 0.65% | 28 | $151.06 |
| 2 | 13.20% | 5.14% | 5.51% | 39 | $247.22 |
| 3 | 7.98% | 8.28% | 9.43% | 39 | $235.35 |
| 4 | 13.28% | 11.27% | -4.04% | 38 | $209.83 |
| 5 | 8.47% | -1.11% | 2.35% | 21 | $126.26 |
No matching rows. Clear the filter to see all records.
Native source statistics, fresh $10,000 per outer test. These are retrospective development periods, not certified unseen observations.
The historical export retains a 100.1% sell size. Current-builder acceptance has not been verified for this value. Before recreating a candidate, validate the full export; any correction must be saved and tested as a new version while the original evidence remains intact.
The configuration preserves the legacy stored sell size of 100.1% of the position. The rule illustration summarizes that as selling the held position; it does not replace the original value. Positive EMA-value checks in the seed are warmup checks, not additional price-versus-EMA trend tests.
MCP run_walk_forward_study supports preview_only with your verified portfolio_id. Native Aurora chat rejects a preview-only launch. Launch and result retrieval require your own account; result retrieval can materialize winner portfolios. No private account, strategy or research-job identifiers appear in this public example.
No comments yet.